

BILL Spend & Expense (Divvy)
4.5

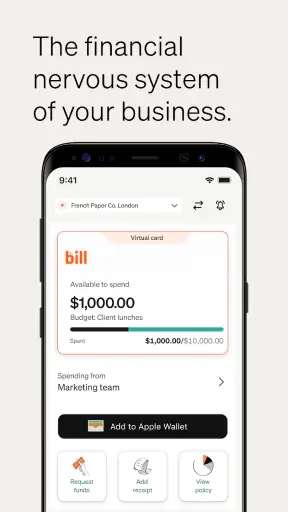
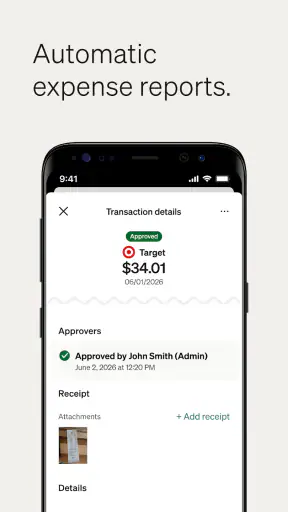
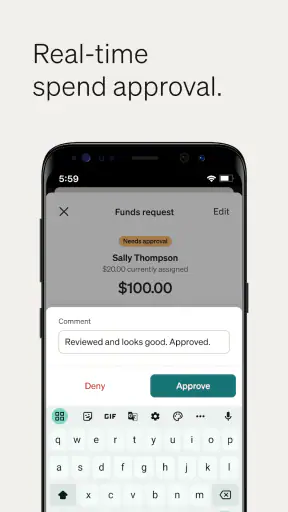
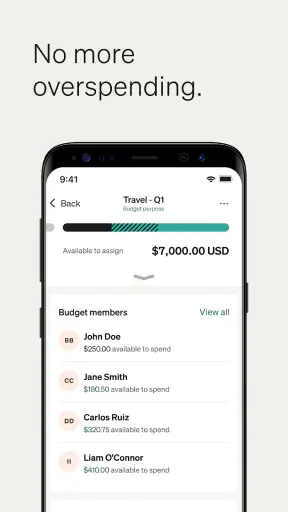
I found BILL Spend & Expense most useful when I treated it as a work-control tool rather than just another payment app. It is a free business application from Bill.com Inc. for managing corporate cards and employee spending, and its real value appears after a team agrees on how purchases should be recorded and reviewed. The app can make routine expense work feel less scattered, but it is not a replacement for a complete accounting system or a personal budgeting app.
My first impression was that the product is aimed at companies that want spending activity to be visible while purchases are still happening. That makes it relevant to owners, finance staff, department managers, and employees who regularly buy things for work. If you only need to track your own household expenses, I would choose something simpler. If several people spend company money and the follow-up is currently handled through email, paper receipts, and spreadsheets, this is where the app starts to make sense.
What to expect before you begin
The store summary describes the core idea plainly: corporate cards combined with expense management. In everyday use, that means the app belongs to the business category, not the consumer banking category. I would approach it expecting a shared workflow around company spending, with employees and reviewers looking at the same activity from different perspectives.
The app is free to install and has an Everyone content rating, which makes it easy to consider for a mixed workplace. It has passed the early-adoption stage too, with more than one hundred thousand installs and a 4.5 average from about four thousand ratings. Those figures do not guarantee that every company will find the workflow comfortable, but they do suggest that the product is being used beyond a tiny test audience.
One important expectation-setting point is that your experience will depend on your role. An employee who needs to document a purchase may see the app as a quick reporting tool. A manager may care more about checking spending context. Someone responsible for finance will judge it by how much chasing and reconciliation it removes. I would not evaluate it from only one of those viewpoints.
The current release is version 4.0.17 and requires operating system version 12 or later. That requirement matters before you ask a whole team to install it. A company with older phones or devices that cannot be updated should check compatibility first, because a smooth rollout is impossible if the people making purchases cannot access the app.
Who gets the most from it
I see the strongest fit in a small or mid-sized organization where spending is distributed among several people but financial oversight is still relatively hands-on. A sales representative buying supplies, a project lead paying for a service, and an office manager handling recurring purchases all create the kind of activity that becomes difficult to organize when every receipt follows a different path.
It can also suit a business that wants employees to take responsibility for the context behind a purchase instead of handing finance a pile of unexplained transactions. That distinction is important. The app is not valuable merely because it displays spending; it is valuable when the people involved use that visibility to create a cleaner record.
I would be more cautious for a freelancer with one bank account, a very small number of monthly expenses, or no need for corporate cards. A basic spreadsheet may be faster and more flexible in that situation. I would also hesitate if your main requirement is full bookkeeping, tax preparation, payroll, or invoicing. BILL Spend & Expense may support the spending side of a process, but those broader jobs call for dedicated tools.
Getting through the first setup
For a first-time user, the most reassuring approach is to start with the company’s intended workflow rather than tapping around randomly. Before installing it for everyone, decide who will make purchases, who will review them, and what information should accompany an expense. Even a short internal agreement prevents the app from becoming another place where incomplete records accumulate.
I would begin by confirming that the phone meets the operating-system requirement, then install the app and sign in through the business arrangement provided by the organization. The important practical question is not simply whether you can open the app; it is whether your account has the right relationship to the company’s spending process. If you are an employee and do not see the expected company context, that is usually a setup issue to resolve with the administrator rather than something to keep guessing at inside the app.
During onboarding, keep a real work purchase in mind. A recent office supply, client-related expense, or travel item is better than a hypothetical example because it gives you something concrete to verify. You want to know where the transaction appears, where supporting information belongs, and how the item becomes ready for someone else to review.
My best setup tip is to test one complete transaction before inviting the whole team. That small pilot exposes unclear responsibilities early. If the employee assumes a manager adds the missing context, while the manager assumes finance does it, the problem will repeat across every purchase. A single test reveals the gap while it is still easy to fix.
The first meaningful success
The first success I would aim for is not merely logging in or viewing a card. It is taking one genuine business purchase from visible transaction to understandable expense record. That gives you a practical answer to the question every new user has: “What am I expected to do here?”
Open the relevant spending activity, identify the purchase, and add the details your organization uses to explain it. If a receipt or supporting document is part of your company’s routine, attach it while the purchase is still fresh. Then check the result from the perspective of the next person in the chain. Could a manager understand what the purchase was for without sending you a message? Could finance distinguish it from a similar transaction later?
This is where the app can be more useful than a loose collection of email attachments. An email may prove that a receipt was sent, but it does not necessarily place that receipt beside the transaction or make the business purpose easy to find. A spreadsheet can hold descriptions, but it often depends on manual copying. The benefit here is the connection between the spending event and the explanation around it.
A realistic example would be an employee buying materials for a client visit. Immediately after the purchase, the employee records the business reason and supplies the supporting information. The manager can then review the item while the context is still clear, instead of asking several weeks later what an unfamiliar charge meant. The time saved is not just the tapping involved; it is the avoided back-and-forth.
Another useful habit is to treat the app as a same-day checkpoint. Waiting until the end of the week may seem harmless, but memory fades and receipts get separated from the transaction. A quick update after each purchase creates a more reliable record and makes the eventual review less intimidating.
Where new users may hesitate
The first common confusion is the difference between seeing a transaction and completing the expense work around it. A card charge can be visible before it has all the information a reviewer needs. I would not assume that visibility means the item is finished. Look for the signals your workflow uses to show that the record is ready for review, and make sure the description and supporting material are actually attached to the correct purchase.
A second source of friction is role confusion. The person who made a purchase may be responsible for explaining it, while a manager or finance colleague handles the review. If you are unsure whether an item needs another action, ask who owns the next step instead of repeatedly editing the same record. Clear ownership is especially important in teams where some people use corporate cards frequently and others only occasionally.
Another subtle issue is timing. A user may open the app immediately after paying and expect every detail to appear at once. Spending information can require a moment to become useful in context, so I would avoid treating a temporarily incomplete view as proof that something went wrong. Refreshing once and checking the transaction later is more sensible than creating a duplicate manual record.
Receipts can create their own uncertainty. A photo is only helpful if it is readable and connected to the right purchase. I recommend checking the image before moving on, particularly when several expenses happened on the same day. A blurry or ambiguous receipt may technically be present but still leave the reviewer with the same question as before.
There is also a behavioral trap: adding excessive commentary. Good expense notes explain the business purpose, not every detail of the day. “Materials for the client demonstration” is more useful than a long personal narrative. The goal is to make the record understandable to another person months later without turning every entry into a report.
Making the workflow work for a team
Once the first transaction is complete, the next step is consistency. I would encourage a team to agree on a short standard for descriptions, receipt handling, and review timing. The app can organize spending, but it cannot decide what your company considers a clear explanation. That shared standard is what turns individual entries into a dependable business record.
A practical routine is to review spending in small batches rather than waiting for a large monthly cleanup. Managers can look for unclear business purposes while the employee still remembers the purchase. Finance staff can spot patterns in missing information without having to reconstruct an entire period. This is one of the less obvious advantages of using a dedicated expense workflow: it shifts questions closer to the moment they arise.
I also recommend separating “needs clarification” from “looks unusual.” An unfamiliar purchase may be legitimate, while a familiar purchase may still be poorly documented. If your team treats every question as an accusation, employees may avoid the process. If every item is waved through, the app becomes a passive archive. The best use is a calm review habit focused on making records understandable.
For managers, the useful question is not only whether an employee spent money, but whether the spending connects to a valid work activity. For employees, the useful question is not only whether a receipt was uploaded, but whether a colleague could interpret the transaction without extra context. Those two viewpoints help prevent the app from becoming a checkbox exercise.
How it compares with familiar alternatives
Compared with a spreadsheet, BILL Spend & Expense offers a more natural home for transaction-based work, especially when multiple people participate. A spreadsheet can be customized endlessly, but that flexibility often creates inconsistent columns, delayed updates, and unclear ownership. I would still choose a spreadsheet for a tiny operation that values complete control over layout and has very few purchases.
Compared with sending receipts by email, the app has a clearer relationship between the purchase and its documentation. Email is quick for one-off communication, but it becomes difficult to search and review when messages arrive from many employees. If your current system already has disciplined receipt naming and a strong filing process, the difference may be smaller; for a busy team, the structured workflow is more compelling.
Compared with a personal finance app, this product is better aligned with company spending and shared responsibility. Personal finance tools are usually designed around one person’s household view, not a workplace where an employee records a purchase and another person evaluates it. I would not use a consumer budgeting app as a substitute simply because it looks easier.
Compared with a full accounting platform, the trade-off is focus. Accounting software may cover a wider set of financial tasks, but it can feel excessive for an employee who only needs to document a company purchase. BILL Spend & Expense is more attractive when the immediate problem is spending visibility and expense follow-up. If you need ledgers, tax workflows, invoicing, and broader financial reporting in one place, look beyond this app or use it only as one part of the process.
Small habits that reveal its value
One useful habit is to write the purpose before attaching the receipt. The purpose is usually the information most likely to be forgotten, while the receipt is easier to locate at the time of purchase. Doing the explanation first encourages a meaningful note instead of a rushed upload with no context.
A second is to review recurring purchases for clarity rather than assuming repetition makes them self-explanatory. A monthly service or regular supply order may look obvious to the buyer but unfamiliar to a new manager or auditor. A brief, consistent explanation helps the record survive staff changes.
A third is to use the first week as a process test, not a performance test. Watch where people pause, which instructions they misunderstand, and which transactions need follow-up. Then simplify the internal guidance. The app becomes easier when the company removes unnecessary decisions around it.
These habits matter because expense management is partly a human coordination problem. No interface can make a vague purchase description useful or make an unassigned review happen automatically through goodwill alone. The strongest results come when the app supports a rule that the team already understands.
When I would recommend skipping it
I would skip this app if you are looking for a private spending tracker for groceries, rent, subscriptions, and personal goals. Its business orientation would add structure you do not need. I would also skip it if your company never uses corporate cards and has only a handful of expenses that one person can reconcile without help.
It may not be the right choice for a team that wants complete freedom to design every field and workflow from scratch. A spreadsheet or specialized accounting product may offer more customization, even if it demands more manual discipline. Likewise, businesses with complex financial requirements should judge it as a spending component rather than assume it covers every accounting responsibility.
Finally, I would not recommend rolling it out without a clear owner. If nobody is responsible for explaining the process, checking incomplete records, and helping with account access, adoption can stall regardless of how polished the app feels. The technology works best when the organization has already decided what good expense documentation looks like.
My next-step recommendation
After installing it, I would not try to configure an entire company in one sitting. Start with one employee, one real transaction, and one reviewer. Confirm that the purchase can be found, explained, supported, and understood by the next person. That is the shortest path to a meaningful result and the best way to discover whether the workflow fits your business.
Then introduce a simple routine: record purchases promptly, add the business purpose in plain language, check supporting documents for readability, and resolve questions while the details are fresh. Those steps are more important than exploring every screen on day one. They create the practical value that a store summary cannot show.
With a 4.5 average across roughly four thousand ratings, the app has a solid public reception, and I can understand why it appeals to teams trying to bring corporate spending into one process. My recommendation is positive for businesses that need shared visibility and cleaner expense follow-up. I would be less enthusiastic for personal finance or full accounting needs.
BILL Spend & Expense is at its best when it turns “What was this charge?” into a question that has already been answered. If your team is willing to build the small habits around it, the free app can make everyday corporate spending easier to document and review. If your current process is already simple, or your needs extend far beyond expenses, a different tool may be the more sensible choice.
4.5
555.00 Reviews
Pros
- Real-time spending visibility helps teams monitor budgets as purchases happen.
- Virtual cards can reduce exposure when shared with employees or vendors.
- Receipt capture makes it easier to keep transaction records organized.
- Custom approval rules support different spending limits across departments.
- Useful reporting tools can simplify month-end expense reviews.
Cons
- Some features may require a paid business plan or administrator setup.
- Employees may need training before using cards and expense workflows correctly.
- Limited value for individuals who do not manage business spending.
- Bank and accounting integrations may vary by country or provider.
- Mobile features depend on reliable internet and accurate receipt uploads.


